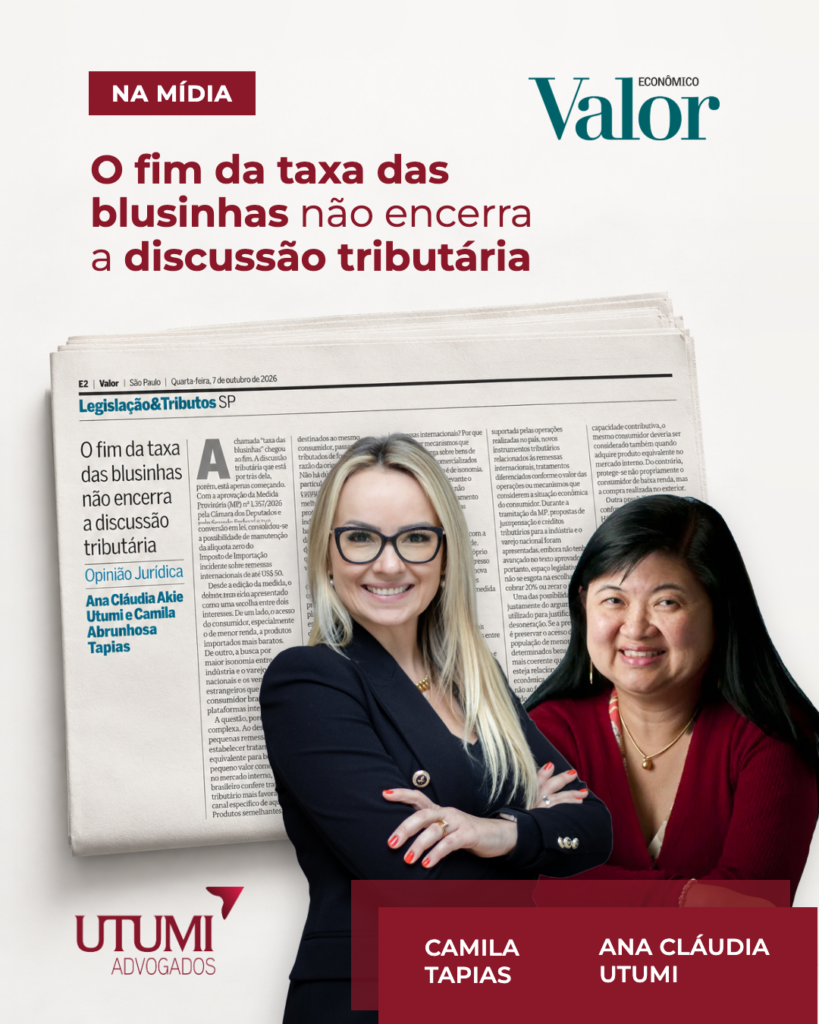
Our partners Ana Cláudia Utumi and Camila Tapias published an article in newspaper Valor Econômico analyzing why the elimination of the “blusinhas” tax does not put an end to the tax debate.
With the conversion of Provisional Measure No. 1,357/2026 into law, the zero import tax rate on international shipments of up to US$50 was consolidated, without equivalent treatment for low-value goods sold on the domestic market. Similar products, intended for the same consumer, are now taxed differently based on the origin of the transaction.
Ana and Camila argue in the article that, between charging 20% and setting the tax to zero, there is room for alternatives more compatible with equality, the ability to pay, and tax neutrality—such as linking the benefit to the consumer’s economic status, as exemplified by the IBS and CBS refunds provided for in Constitutional Law No. 214/2025.